Ascent CFO Solutions made the Inc. 5000 List of America’s Fastest Growing Private Companies!

Author: Ascent CFO

How to Job-Cost a Construction Project So It Actually Makes Money

Key Takeaways

  • Job costing is tracking the true cost of each project (fully burdened labor, materials, subcontractors, equipment, and a share of overhead) against what you bid, so you know which jobs make money and which lose it. Run it during the job, not after.
  • Most contractors price off a rough markup and never compare actual cost to the estimate until a job closes, by which point the margin is already gone. The profit leaks are predictable: unburdened labor rates, unpriced change orders, and margin fade between the bid and the final number.
  • The fix is a system, not a spreadsheet at year-end: estimate in the same cost codes you track actuals in, watch committed costs as they happen, and review each job’s cost against its budget every month while you can still act on it.

You finished the big job last month. On the bid it looked like a solid twenty percent margin, the crews worked hard, the client was happy. Then you looked at the bank account and the money was not there. Somewhere between the estimate and the final cost, the profit disappeared, and if someone asked you exactly where, you could not say. That gap, between the margin you bid and the margin you actually earned, is the single most expensive blind spot in a growing construction company, and job costing is how you close it.

Job costing means knowing the real cost of each individual project, tracked against what you estimated, in enough detail to see problems while the job is still running. Done well, it tells you which jobs and which types of work actually make money, so you bid the next one smarter and catch the losers before they finish losing. Done poorly, or not at all, you run the company on a single company-wide profit number that tells you whether last year worked but nothing about why. Here is how to do it well.

Why the Bid Is Not the Profit

A bid is a prediction. Profit is what is left after reality happens to that prediction. Between the two sit a handful of leaks that drain margin on almost every job, and the contractors who stay profitable are the ones who track them in real time rather than discovering them at close-out.

  1. Unburdened labor. The wage you pay a worker is not what that worker costs. Add payroll taxes, workers’ compensation, benefits, and unproductive time, and the fully burdened cost of labor commonly runs 25% to 35% above the base wage.If you estimate and track labor at the base rate, every hour on every job is underpriced, and labor is usually your largest and most variable cost.
  2. Unpriced change orders. The client asks for a change, your crew does the work to keep things moving, and the paperwork never catches up. Work performed without a signed, priced change order is work you did for free. On a busy job, unbilled changes become one of the largest sources of lost margin, because the cost lands in your numbers and the revenue never does.
  3. Margin fade. This is the slow erosion between the bid and the final cost: a little more labor here, a materials price increase there, a subcontractor overrun, a week of weather. No single item is alarming, but together they turn a twenty percent bid into a ten percent result. Margin fade is invisible unless you are comparing actual cost to budget while the job runs.
  4. Missing overhead allocation. Direct costs are only part of the picture. Your office, your estimators, your equipment, your insurance: every job has to carry a share of that overhead, or a job that looks profitable on direct costs alone is actually underwater once the business behind it is paid for.

The reason these leaks persist is timing. A contractor who reviews costs only when a job closes learns about every one of them too late to do anything. The whole point of job costing is to move that discovery earlier.

What a Real Job-Costing System Looks Like

Job costing is not a heroic spreadsheet you build once a year. It is a small set of disciplines that run continuously, and none of them require enterprise software to start.

Estimate in the same structure you track actuals. Build your bid in cost codes (labor, materials, subs, equipment, by phase) and record actual costs against those same codes. If the estimate and the accounting do not share a structure, you can never compare them cleanly, and the comparison is the entire value of job costing.

Track committed costs, not just paid costs. The moment you issue a purchase order or sign a subcontract, that money is committed even though no invoice has arrived. A job-costing view that shows only paid costs understates where a job actually stands. Committed-cost tracking is what lets you see an overrun coming instead of confirming it after the check clears.

Review cost against budget every month, by job. This is the work-in-progress review, and it is where margin fade becomes visible while you can still act. Comparing the cost you have incurred to the percentage of work complete tells you whether a job is tracking to its bid or drifting, on a timeline that still allows a correction. This is the same discipline that keeps work-in-progress and cash cycles under control on construction and real estate projects.

Close out every job with a review that feeds the next bid. When a job finishes, compare final cost to the original estimate, code by code, and carry what you learned into the next proposal. Contractors who do this get better at bidding with every project. The ones who do not repeat the same estimating mistakes indefinitely.

Pricing the work correctly is the other half. The Billd 2025 National Subcontractor Market Report found that contractors who priced the cost of carrying a job into their bids earned a 24% profit margin, versus 17% for those who did not. Job costing gives you the actual numbers to price that way, instead of guessing at a markup.

Speak to a CFO

A contractor who cannot say which jobs make money is flying without instruments, and the fix is a job-costing system that fits how you already work. A fractional CFO who knows construction can set up your cost codes, stand up committed-cost and WIP tracking, and turn your close-out data into sharper bids. Book a CFO strategy call with Ascent CFO Solutions and we will show you where your margin is actually going.

What Good Looks Like

A contractor with real job costing in place can answer a simple question at any point in a project: is this job going to make what we bid? The estimate and the books share a structure, so actual cost drops against budget automatically. Committed costs are visible the day they are committed, not the day they are invoiced. A monthly WIP review flags the jobs drifting off budget while there is still time to manage them. And every completed job sharpens the next estimate instead of repeating the last one’s mistakes.

The payoff shows up in two places. Margins stop leaking, because fade and unbilled changes get caught mid-job. And bidding gets better, because you are pricing from what work actually costs rather than from a markup you have never checked against reality. That combination is how construction companies grow revenue and grow profit at the same time, rather than getting busier without getting richer. It also depends on the cash side holding up, which is why job costing pairs with understanding why a full backlog can still leave you short on cash.

Talk to a CFO
An Experienced CFO is Within Reach

Get right-sized financial leadership from experienced CFOs ready to lead your team.

Frequently Asked Questions

What is job costing in construction?

Job costing is tracking the actual cost of an individual project (labor, materials, subcontractors, equipment, and allocated overhead) against the estimate you bid, in enough detail and often enough that you can see how the job is performing while it is still running. It tells you which jobs and types of work make money, rather than only whether the company as a whole was profitable.

Why is my construction company busy but not profitable?

Usually because margin is leaking on individual jobs and no one is tracking it in time to stop it. The common culprits are labor costed at the base wage rather than its fully burdened rate, change orders performed without being priced and billed, and margin fade, the slow drift between the bid and the final cost. Without job costing, all of these surface only after the job closes, too late to fix.

What is fully burdened labor cost?

It is the true cost of an hour of labor, including payroll taxes, workers’ compensation, benefits, and unproductive time, not just the base wage. Fully burdened labor commonly runs well above the base rate, so estimating and tracking labor at the base wage understates the cost of every job. Labor is typically a contractor’s largest and most variable cost, which makes this the most important number to get right.

What are committed costs and why do they matter?

Committed costs are amounts you have obligated through purchase orders and signed subcontracts but not yet paid. Tracking them matters because a job-costing view based only on paid invoices understates where a job really stands and hides overruns until the bills arrive. Watching committed costs lets you see a problem coming while you can still act on it.

How is job costing different from a WIP schedule?

They work together. A work-in-progress schedule tracks billings and costs against percent complete across your jobs, largely for cash-flow and accounting purposes. Job costing goes deeper on the cost side of each job, comparing actual cost to the estimate by cost code so you can manage profitability. The WIP review is often where job-cost problems first become visible.

Turning Busy Into Profitable

We help construction and real estate companies in Boulder, Denver, and across the country put job costing in place so they can price, track, and finish work at the margin they intended. That work spans fractional CFO leadership, clean fractional accounting structured around cost codes, and the cash flow forecasting that keeps a growing book of work liquid. See how we work with contractors and developers on our construction and real estate page.

Book a CFO strategy call with Ascent CFO Solutions.

Why Do Growing Construction Companies Run Out of Cash Even With a Full Backlog?

Key Takeaways

  • A full backlog is a promise of future revenue, not cash in the bank. Construction companies fund payroll, materials, and subcontractors for weeks or months before the owner pays, so faster growth widens the gap between cash going out and cash coming in.
  • The drains are structural, not a sign you are running the business poorly: slow progress billing, retainage held back on every job (commonly 5% to 10%), over- and under-billing that hides your true cash position, and collection times far longer than most contractors expect. Billd’s 2025 National Subcontractor Market Report, which surveyed more than 800 construction professionals, found subcontractors wait an average of 56 days to get paid while general contractors believe payment happens within 30.
  • The best practice solution is a rolling cash flow forecast tied to your work-in-progress schedule, disciplined billing, and bids that price in the cost of carrying each job. Contractors who accounted for working-capital cost in their bids earned 24% margins versus 17% for those who did not.

The backlog has never been bigger. The phone keeps ringing, you are turning down work, and by every measure the business is winning. Then Friday comes and payroll is tight again. You are profitable on paper and scraping to cover the week. If that describes your company, nothing is wrong with your judgment. You have hit the structural cash problem that catches almost every construction company as it grows, and it gets worse, not better, the more work you take on.

Here are the mechanics underneath it. In construction you spend money to build before the owner pays you for building. You cover labor, materials, and subs for a project up front, bill in arrears, wait through the owner’s payment cycle, and then watch a slice of what you earned get held back as retainage until the whole job closes. Every new project you win is a cash outflow before it is ever a cash inflow. So a growing backlog is a growing pile of jobs you are financing yourself. Understanding that working capital gap, and managing it deliberately, is the difference between a contractor who scales and one who stalls out while fully booked. 

Why a Full Backlog Makes the Cash Problem Worse

Most industries collect cash close to when they deliver. Construction does not. You mobilize a crew, buy materials, and pay subcontractors weeks before you can bill for that work, and then weeks or months more before the money arrives. The size of that gap is your working capital requirement, and it scales directly with volume. Double your revenue and you roughly double the amount of cash you have tied up in jobs at any given moment.

That is why the healthiest-looking growth can create the tightest cash squeeze. A contractor going from $8 million to $15 million in revenue is not just doing more work. They are carrying far more unpaid cost at every point in the month. The backlog says the future is bright. The bank account says you are funding that future out of pocket right now. Both are true at the same time, and the second one is what makes payroll hard.

The Four Structural Cash Drains on a Growing Contractor

The gap between profitable and liquid comes from four specific places. Naming them is the first step to managing them.

  1. Slow progress billing and slower payment. You bill as work completes, then wait through the owner’s cycle. The wait is longer than most contractors budget for. That 26-day gap between expectation and reality is cash you are financing without having planned to.
  2. Retainage. On most jobs the owner holds back a percentage of every payment, commonly 5% to 10%, until the project is complete and accepted. That retained money is profit you have already earned and cannot touch, sometimes for months after your costs are paid. Across several active jobs, retainage alone can tie up a meaningful share of your annual margin.
  3. Over- and under-billing. This is the one that hides the problem. If you bill ahead of the work you have completed (overbilling), you are borrowing cash from the job that will have to be repaid in effort later. If you bill behind the work (underbilling), you have already spent the money and have not asked for it yet. Both distort what your cash position actually is, and you cannot see either one without a work-in-progress schedule tracking billings against costs on every job.
  4. Underpriced work. If your bids do not account for the cost of carrying a job for two or three months, you are giving that financing away. The Billd data makes the cost of ignoring this concrete: contractors who factored working-capital cost into their pricing earned a 24% profit margin, compared with 17% for those who did not.

The 43% of subcontractors who told Billd they lack enough working capital to cover an unexpected expense or a project delay are not badly run companies. They are companies whose growth has outrun their cash cycle, which is the default state of a busy contractor who has not yet built the financial discipline to manage it.

Talk to a CFO
An Experienced CFO is Within Reach

Get right-sized financial leadership from experienced CFOs ready to lead your team.

Why Your P&L Says You Are Fine

The confusing part is that your profit-and-loss statement can look healthy through all of this. That is a function of how construction revenue is recognized, not a mistake. Under the percentage-of-completion method that most contractors use, and that the FASB’s revenue standard (ASC 606) governs, you recognize revenue and profit as a job progresses, based on how much of the work is done. You book the profit on the calendar of the work, not the calendar of the cash.

So a job that is 60% complete shows 60% of its revenue and profit on your income statement, even if the owner has paid you for only 40% and is holding retainage on top of that. Your P&L is telling you the truth about profitability and saying nothing about liquidity. This is why so many construction owners are blindsided: they are reading a report that was never designed to tell them whether they can make payroll. The document that answers that question is a cash flow forecast tied to the work-in-progress schedule, and most growing contractors do not yet have one. It is also why construction cash flow deserves its own discipline, distinct from the accounting that produces the financial statements. We go deeper on the accounting mechanics in our guide to managing WIP and cash cycles in construction and real estate.

Speak to a CFO

A contractor with a full backlog and a tight bank account does not have a profitability problem. You have a cash-timing problem, and it is solvable with the right forecast, billing discipline, and pricing. A fractional CFO who knows construction can build the model that shows you your cash position weeks ahead, before the tight Friday arrives. Book a CFO strategy call with Ascent CFO Solutions and we will help you turn a busy year into a liquid one.

What Good Looks Like

Contractors who grow through the cash squeeze instead of stalling in it tend to have the same handful of habits in place.

A rolling cash flow forecast, tied to the WIP schedule, that projects cash 13 weeks out by job. This is the core instrument. It takes each active project’s billing schedule, cost curve, retainage, and expected payment timing and turns them into a week-by-week view of what the bank balance will actually be. It is the report your P&L cannot give you, and it is where a tight week becomes visible while there is still time to act. Our cash flow forecasting work is built around exactly this model.

Disciplined billing. Bill on time, every cycle, for everything earned, and chase retainage release the day a job qualifies for it. The single fastest way to improve construction cash flow is to stop leaving earned money on the table because the paperwork slipped.

Pricing that carries the job. Build the cost of financing a project for its full payment cycle into the bid, the way the 24%-margin contractors in the Billd survey do. Money you spend carrying a job for 60 days is a real cost, and work that does not price it in is less profitable than it looks.

A line of credit sized to the cash cycle, arranged before you need it. A revolving facility exists precisely to bridge the gap between paying costs and collecting revenue. Among larger subcontractors in the Billd survey, 41% seek working capital before they need it, which means a majority still wait until they are already squeezed. The time to set up the line is when the numbers are strong, not when payroll is short.

Consider a specialty contractor doubling revenue over two years while staying fully booked, yet fighting to make payroll every few weeks. Building a WIP-linked 13-week forecast surfaced the real issue in a week: the company was underbilled across three large jobs and carrying retainage worth more than a month of overhead. Fixing the billing cadence and drawing on a properly-sized line-of-credit closed the gap without touching the work itself. The backlog was never the problem. The cash cycle behind it was.

Frequently Asked Questions

Why is my construction company profitable but always short on cash?

Because construction recognizes profit as work is completed but collects cash much later. You pay for labor, materials, and subcontractors up front, bill in arrears, wait through the owner’s payment cycle, and have retainage held back until the job closes. Your P&L shows the profit on the timeline of the work; your bank account reflects the much slower timeline of the cash. Growth widens that gap, so a busy, profitable contractor can be the tightest on cash.

What is retainage and how much do contractors hold back?

Retainage is a portion of each payment the owner withholds until the project is complete and accepted, commonly 5% to 10%. It is money you have already earned and cannot access, sometimes for months after your costs on that work are paid. Across multiple active jobs, retainage can tie up a significant share of your annual profit, which is why tracking and chasing its release is an important cash-flow habit.

What is a WIP schedule and why does it matter for cash flow?

A work-in-progress (WIP) schedule tracks each active job’s costs, billings, and percentage complete, and shows whether you are overbilled or underbilled on every project. It matters because over- and under-billing hide your true cash position: overbilling borrows cash you will owe back in future work, and underbilling means you have spent money you have not requested. Without a WIP schedule you cannot forecast cash accurately or spot a squeeze before it hits.

How long does it take to get paid in construction?

Longer than most contractors plan for. That gap between expectation and reality, multiplied across every active job, is a major reason growing contractors run short on cash despite strong backlogs.

How much working capital does a construction company need?

Enough to fund all the labor, materials, and subcontractor costs you carry between paying for work and collecting on it, across every active job at once. That number scales with revenue, so it climbs as you grow. A rolling cash flow forecast tied to your WIP schedule is the tool that tells you the actual figure for your business, and a line of credit sized to that cycle is how most contractors bridge it.

Turning a Busy Year Into a Liquid One

We help construction and real estate companies in Boulder, Denver, and across the country build the financial discipline that lets them grow without running out of cash. That work runs from a WIP-linked cash flow forecast to clean fractional accounting and the fractional CFO leadership to price, bill, and finance jobs the way a profitable contractor should. See how we work with contractors and developers on our construction and real estate page, and if this squeeze sounds familiar, these reads go deeper: why cash flow kills more profitable companies than you think and who needs a 13-week cash flow model.

Book a CFO strategy call with Ascent CFO Solutions.

Which EBITDA Add-Backs Will a Buyer Actually Accept?

Key Takeaways

  • An add-back is an expense you argue is not a true cost of the ongoing business, so it gets added back to EBITDA and raises the earnings number a buyer’s multiple applies to. Done well, add-backs legitimately raise your sale price. Overreached, they cost you credibility.
  • Buyers accept add-backs that are genuinely one-time, non-operating, or tied to the current owner (a lawsuit settlement, above-market owner pay, personal expenses run through the company) when each of them is documented. They reject anything recurring, or unsupported.
  • Every add-back a buyer rejects represents EBITDA removed, multiplied by your multiple. At a 6x multiple, a rejected $200,000 add-back is $1.2 million off your price. Build and document the schedule before diligence, on your terms, not under the buyer’s questioning.

Your adjusted EBITDA is $4 million. Your books EBITDA, the number that falls straight out of the financials, is $3 million. The difference is a one-page schedule of add-backs: the owner’s salary above market, a legal settlement, personal travel, a discontinued product line, a few things that are harder to explain. When you sell, a buyer’s quality-of-earnings team will go down that page line by line and decide which adjustments survive. Every one they accept, they pay a multiple on. Every one they strike, they subtract, and then multiply the loss. That page is one of the most valuable documents in the entire transaction, and most founders build it badly.

Add-backs are legitimate. Normalizing earnings to show what the business really produces under a new owner is exactly what they are for, and a well-built schedule can add real dollars to your price. The problem is that the line between a defensible add-back and wishful thinking is where deals get re-traded, and founders consistently put items on the wrong side of it. Here is how a buyer actually decides.

Why an Add-Back Is Worth More Than a Dollar

Start with the math, because it is what makes this worth getting right. A buyer values your company as a multiple of EBITDA. If your business trades at 6x and you can legitimately add back $300,000 of owner-specific and one-time costs, that is not $300,000 of value. It is $1.8 million, because the multiple applies to the adjusted number. The effect runs in both directions. An add-back the buyer rejects does not just lower EBITDA by its face value; it lowers the price by that amount times the multiple.

That is why the quality of your add-back schedule moves the deal more than almost any other single document. Buyers are also underwriting your earnings harder than they used to. Bain & Company notes that returns now depend on growing EBITDA rather than financial engineering, with deals requiring 10% to 12% annual EBITDA growth to hit target returns. A buyer building a plan on your earnings is going to test every dollar of the base they are starting from, which means every adjustment gets scrutinized.

The Add-Backs Buyers Accept

Legitimate add-backs share a trait: the expense genuinely will not exist, at that level, for the business going forward under a normal owner. These are the categories a buyer will generally allow when you can support them.

  1. One-time, non-recurring costs. A lawsuit settlement, an office move, severance from a reorganization, the cost of a failed product launch you have discontinued. Genuinely singular events that will not repeat are the cleanest add-backs, provided you can show they were actually one-time.
  2. Above-market owner compensation. If you pay yourself $500,000 and the market rate for your role is $250,000, the $250,000 difference is a defensible add-back, because a new owner would pay market. The reverse also applies: if you underpay yourself, the buyer will subtract the difference, so the adjustment has to reflect a real market rate.
  3. Personal or discretionary expenses run through the company. The car, the family member on payroll who does not substantially work in the business, the club membership, the personal travel. Real, documentable personal expenses that a new owner would not incur are legitimate, and they are also the ones a buyer examines most skeptically.
  4. Non-operating items. Income or expense unrelated to running the business, such as a gain on selling an asset or a one-time insurance recovery, gets normalized out because it does not reflect ongoing operations.

The common thread is documentation. Each of these is defensible only if you can put support behind it, and each is a red flag to a buyer if you cannot.

The Add-Backs Buyers Reject

Rejected add-backs almost always fall into a few predictable traps. A buyer’s quality-of-earnings team sees these constantly and strikes them quickly.

Recurring costs dressed up as one-time. The “one-time” consulting project that shows up in three consecutive years is not one-time. If a cost recurs, it is part of the business, whatever you call it. Speculative run-rate adjustments come next: adding back to reflect revenue you expect but have not earned, or savings you plan but have not made, asks the buyer to pay a multiple on a projection which will likely be challenged. Owner-compensation claims that exceed a defensible market rate get adjusted to that rate. And the largest category is anything undocumented. An add-back you cannot support with an invoice, a contract, or a clear record is one the buyer removes, because they cannot verify it and will not pay for what they cannot verify. The way a buyer thinks about earnings quality, which the CFA Institute defines as the degree to which reported profit reflects genuine, repeatable performance, leaves no room for adjustments that cannot be proven.

Speak to a CFO

Building an add-back schedule that survives diligence is finance work, and the time to do it is before a buyer is at the table, not while their team is questioning you. A fractional or interim CFO can construct the schedule, assemble the support for every line, and defend it under scrutiny. Book a CFO strategy call with Ascent CFO Solutions and we will help you build a schedule a buyer will actually accept.

Talk to a CFO
An Experienced CFO is Within Reach

Get right-sized financial leadership from experienced CFOs ready to lead your team.

Why Overreaching Costs More Than the Rejected Line

The temptation is to load the schedule and let the buyer negotiate down. That instinct is expensive, and not only because of the struck lines. When a buyer finds one add-back that does not hold up, they do not just remove it. They start to distrust the entire schedule, and they discount adjustments they might otherwise have accepted. One indefensible line makes every other line look like a stretch. A padded schedule can lower your adjusted EBITDA below what an honest, well-documented one would have delivered, because it costs you the buyer’s confidence in the whole number.

The founders who capture the most value do the opposite. They build a conservative schedule where every line has support behind it, so the buyer’s team finds nothing to distrust and accepts the adjustments as presented. A clean schedule that the buyer signs off on beats an aggressive one they tear apart, both in dollars and in the tone it sets for the rest of the deal. Preparing that schedule early, as part of the same quality-of-earnings groundwork that gets you sale-ready, is how you make sure your adjusted EBITDA holds.

Frequently Asked Questions

What is an EBITDA add-back?

An add-back is an expense added back to EBITDA because you argue it is not a true, ongoing cost of the business. Normalizing earnings this way shows what the company would produce under a new owner. Because a buyer applies a valuation multiple to adjusted EBITDA, each accepted add-back raises the sale price by its amount times the multiple.

Which add-backs do buyers accept?

Generally, genuinely one-time costs, above-market owner compensation, documented personal or discretionary expenses run through the company, and non-operating items. The condition is documentation. A buyer accepts an adjustment they can verify with support and rejects one they cannot, regardless of how reasonable it sounds.

Which add-backs do buyers reject?

Recurring costs labeled as one-time, speculative run-rate adjustments for revenue or savings not yet realized, owner-compensation claims are adjusted to market rate, and anything undocumented gets rejected. These are the traps a quality-of-earnings team removes first, and the ones that damage your credibility on the rest of the schedule.

How much can add-backs affect my sale price?

More than their face value, because the buyer applies your multiple to adjusted EBITDA. At a 6x multiple, a $200,000 add-back the buyer accepts is worth $1.2 million of price, and one they reject costs the same. The schedule is one of the documents that most affects your final price.

Should I prepare add-backs before selling?

Yes. Building and documenting the schedule before a buyer’s team arrives lets you find and support every legitimate adjustment on your own terms, present a schedule the buyer trusts, and avoid a mid-deal surprise that lets them re-trade the price. It is a core part of getting sale-ready.

Building a Schedule That Holds

We help founders and CEOs of growth-stage companies in Boulder, Denver, and across the country get sale-ready, including building the add-back schedule and quality-of-earnings support that protect their price. That work spans fractional CFO leadership and mergers and acquisitions support through the deal. If a sale is on your horizon, your adjusted EBITDA is worth building carefully. A few related reads: what is a quality-of-earnings report, is your company ready to be acquired, and how to prepare for the sale of your company.

Book a CFO strategy call with Ascent CFO Solutions.

Selling to Private Equity: What Is Rollover Equity, and How Does the “Second Bite of the Apple” Work?

Key Takeaways

  • When a private equity firm buys your company, you usually do not sell all of it. In a majority recapitalization you sell most of the business for cash today and roll a portion of your proceeds into equity in the new, PE-owned company. That retained stake is rollover equity.
  • The purpose of the roll is the “second bite of the apple”: when the sponsor grows the business and sells it again in roughly five to seven years, your retained stake potentially could be worth as much as, or more than, your first payout. Founders commonly roll 10% to 40% of their proceeds, often in the 20% to 30% range.
  • Rollover is usually structured to defer tax (you are taxed on the cash now and on the rolled equity when the second sale happens), but the second bite is a real investment with real risk. It is worth only as much as the sponsor’s plan and the terms on your stake make it worth.

The offer looks like the outcome you have worked toward for a decade, until you read it closely. The private equity firm does not want to buy all of your company. They want to buy most of it, pay you in cash for that part, and have you “roll” twenty percent of your proceeds back into the new company and stay on to run it. Your first instinct is suspicion. If this is such a good business, why do they want you to keep skin in the game rather than cash you out entirely? The answer is the whole point of the deal, and understanding it is the difference between a smart second payday and a stake you regret keeping.

That retained thirty percent is rollover equity, and the structure is called a majority recapitalization. You sell the majority of your company for cash now, keep a minority piece, and get a second chance to be paid when the private equity firm sells the company again. Founders who understand the mechanics negotiate for a second bite that can rival the first. Founders who do not tend to either refuse a good deal or accept a bad stake. Here is how it actually works.

What Rollover Equity Actually Is

In a full sale, you sell one hundred percent of the company and walk away. In a majority recapitalization, you sell most of it and reinvest part of your proceeds into equity in the post-transaction company the private equity firm now controls. As Carta describes it, you forgo full liquidity on the cash price and instead take a portion of your proceeds as an equity stake in the new enterprise, so you participate in the company’s growth under the sponsor’s ownership.

The size of the roll varies by deal, but it commonly lands somewhere between ten and forty percent of a founder’s proceeds, frequently in the twenty to thirty percent range. On a company that sells for $30 million, a twenty percent roll means roughly $6 million of your proceeds goes back into the new company as equity, and the rest comes to you in cash at close, net of any debt repaid. You take real money off the table now, and you keep a meaningful position in what happens next.

Why the Second Bite Can Be Bigger Than the First

The reason this structure exists is that a private equity firm’s entire business model is to buy a company, make it substantially more valuable, and sell it again at a higher price. They hold portfolio companies for a while to do it. Average holding periods have drifted toward seven years, according to Bain & Company, and in the current environment sponsors earn their returns primarily by growing earnings rather than by financial engineering. Bain notes that a deal today needs 10% to 12% annual EBITDA growth to hit target returns, up from about 5% a decade ago. In other words, the sponsor is highly motivated to make the company bigger, and your rollover stake rides along with that growth.

Consider the simple version. Say your company is worth $30 million today and you roll twenty percent. In an optimistic scenario, over the next six years the sponsor doubles or triples the business and sells it. Your retained stake, if it tracked that growth, could be worth more at the second sale than the cash you took at the first. That is the second bite of the apple: you have already been paid once for the company you built, and you get paid again on the value created after you sold. Real deals are more complicated than that, because leverage, preferred returns, and additional “Add-on” acquisitions all affect how the proceeds divide, and the illustration above is deliberately simplified. But the core mechanic is real, and it is why founders who negotiate rollover well can come out of two transactions ahead of a single full sale.

Why the Private Equity Firm Wants You to Roll

The suspicion that started this is worth answering directly. The sponsor asks you to roll for the same reason it should make you more comfortable, not less: alignment. If you keep a real stake, your incentive to grow the company matches theirs, and you carry some of the risk. A founder who cashes out entirely and stays on as a hired manager is a different kind of partner than one whose own money is invested in the outcome. The roll is the sponsor’s way of making sure the person who built the value is committed to building more of it.

That alignment cuts in your favor when the plan is good. You are effectively co-investing alongside a professional buyer who is putting far more capital at risk than you are, on terms they negotiated for themselves. When the sponsor is capable and the plan is sound, that is a strong position to be in. When the plan is weak, the same alignment means you are tied to it. Which is why the quality of the sponsor and the specifics of your stake matter more than the headline roll percentage.

The Tax Angle

One of the quiet advantages of rolling equity is tax treatment. When structured correctly, a rollover is generally tax-deferred: as Carta notes, only the cash portion of your proceeds is taxable at the time of the sale, and the rolled equity is taxed later, when you cash out at the second sale. You are not paying tax today on money you did not take today. This is a meaningful benefit, but it depends entirely on how the transaction is structured, and the rules are specific. Treat the tax deferral as a reason to involve a qualified tax advisor early, not as something to assume. This is general information, not tax advice, and the structure has to be built correctly to earn the treatment.

Talk to a CFO
An Experienced CFO is Within Reach

Get right-sized financial leadership from experienced CFOs ready to lead your team.

Five Questions That Determine Whether Your Second Bite Pays Off

The roll percentage is the headline, but these are the terms that decide whether rollover equity is a second payday or a trap. Work through them before you sign.

  1. What class of equity are you getting? There is a large difference between rolling into the same security the sponsor holds and rolling into common equity that sits behind the sponsor’s preferred return. If the sponsor gets its money back first with a preferred return before you see a dollar, your second bite is smaller and riskier than the roll percentage suggests. Rolling into the same class as the sponsor is the stronger position.
  2. How much are you rolling, and can you afford to leave it in? Every dollar you roll is a dollar not in your pocket and at risk in a single, illiquid company. The right roll is one you can afford to have tied up for another five to seven years, not the maximum the sponsor will accept.
  3. Is the sponsor’s value-creation plan credible? Your second bite depends on the sponsor actually growing the business. Ask how they intend to do it, what companies they have done it to before, and whether the plan is specific or aspirational. You are underwriting their plan the way they underwrote your company.
  4. What are the terms on your minority stake? Governance, information rights, tag-along and drag-along provisions, and any path to earlier liquidity all shape what your stake is actually worth and how protected you are as a minority holder. A minority position with weak rights is worth less than the same percentage with strong ones.
  5. What happens at the second exit? Understand how you get paid when the company sells again, and how add-on acquisitions between now and then might dilute your stake. Dilution from later deals is one of the most common surprises for rollover holders.

Speak to a CFO

Deciding how much to roll, what class of equity to accept, and whether a sponsor’s plan holds up is exactly the analysis a CFO does best, and it is not a decision to make on instinct with your largest financial event on the line. A fractional or interim CFO can model the second-bite scenarios, pressure-test the value-creation plan, and sit beside you in the negotiation. Book a CFO strategy call with Ascent CFO Solutions and we will help you see what the roll is really worth.

The Risks Worth Naming

Rollover equity is a real investment, and it carries real risk. You are taking less cash now in exchange for an uncertain future payout, and there is no guarantee the equity appreciates enough to make that trade worthwhile. Carta names the main hazards plainly: less immediate liquidity, no assurance the retained stake grows, and possible dilution if the buyer combines your company with other assets. On top of that, if you roll into equity that sits behind the sponsor’s preferred return, a mediocre second exit can pay the sponsor and leave little for you.

None of that makes rolling a bad idea. It makes it a decision to enter with clear eyes and good terms rather than on the assumption that a professional buyer would not offer you anything but a great deal. The founders who do best treat the roll as what it is: a second investment in their own company, made alongside a partner, on terms they negotiated rather than accepted.

Frequently Asked Questions

What is rollover equity in a private equity deal?

Rollover equity is the portion of your sale proceeds you reinvest into the new, private-equity-owned company instead of taking as cash. In a majority recapitalization you sell most of the business for cash and roll a minority stake forward, so you keep a piece of the company and can be paid again when the sponsor sells it later.

What does “second bite of the apple” mean?

It refers to the second payout a founder receives when the private equity firm sells the company again after growing it. Your first bite is the cash at the initial sale; the second bite is the value of your rolled equity at the sponsor’s later exit. Because sponsors aim to grow the business substantially, the second bite can rival or exceed the first.

How much equity do founders typically roll over?

It varies by deal, but rollovers commonly range from about 10% to 40% of a founder’s proceeds, often landing in the 20% to 30% range. The right amount is one you can afford to leave invested and at risk in a single company for another five to seven years, not simply the most the sponsor will take.

Is rollover equity taxed?

Generally, a properly structured rollover defers tax: you are taxed on the cash portion of your proceeds at the sale and on the rolled equity later, when you cash out at the second exit. The treatment depends on how the deal is structured, so involve a qualified tax advisor early. This is general information, not tax advice.

What are the risks of rolling equity?

You take less cash now, your retained stake may not appreciate as hoped, and later acquisitions can dilute your position. If you roll into common equity that sits behind the sponsor’s preferred return, a weak second exit can leave little for you. The risks are manageable with the right class of equity, a credible sponsor plan, and strong minority-holder terms.

Getting Your Second Bite Right

We help founders and CEOs of growth-stage companies in Boulder, Denver, and across the country think clearly about private equity offers, including how much to roll and what the retained stake is really worth. That work spans mergers and acquisitions support and the fractional CFO analysis that pressure-tests a sponsor’s plan before you commit your own money to it. If a recapitalization offer is on your desk, the terms of the roll deserve the same scrutiny as the price. A few related reads: how long PE firms typically hold portfolio companies, will a private equity firm buy your company, and how to prepare for the sale of your company.

Book a CFO strategy call with Ascent CFO Solutions.

scaling

What Are the Financial Blind Spots in a Growing Healthcare or Telehealth Company?

Key Takeaways

  • In a growing healthcare or telehealth company, the financial problem is rarely demand. It is the revenue cycle: how long collection takes, how many claims get denied, and how well payer mix and service-line profitability are actually understood.
  • The blind spots that cap growth are consistent: slow days-in-AR and denied claims leaking collectable revenue, cash-basis books that turn profitability into guesswork, a payer and service-line mix nobody has modeled, and, for telehealth, PHI handling and compliance layered on top.
  • The fix is a finance function built for healthcare economics: reconciled accrual books, revenue-cycle metrics watched weekly rather than yearly, and modeling that ties service mix and utilization to cash.

A telehealth company we looked at was growing fast and breaking even on cash, which sounds fine – until you know the rest. For its model, margins should have been running 10% to 20%. Instead the company was hovering at breakeven while volume climbed, and no one could say exactly why. The books were hand-keyed each day from the CRM into the accounting system, so the numbers were always a little behind and a little uncertain. Somewhere in that gap between growth and cash sat the answer, and it took a finance leader to find it.

That gap is where most growing healthcare businesses lose money they have already earned. Demand is not the constraint. The constraint is a revenue cycle that leaks, books that cannot tell you which services actually make money, and a data flow held together by manual entry. These are finance problems, not clinical ones, and they are solvable. The first step is naming the blind spots.

Why Healthcare Finance Is Different

In most businesses you deliver, you invoice, you collect. In healthcare you deliver care now and get paid later by third parties who can, and frequently do, refuse to pay the first time. Between the visit and the deposit sits the revenue cycle: coding, claim submission, adjudication, denials, appeals, patient balances. Every step is a place where earned revenue slows down or disappears.

That is why the metrics that matter in a healthcare company are not the ones a generalist watches. The industry standard framework, the HFMA MAP Keys from the Healthcare Financial Management Association, is built around exactly these measures: how fast you collect, how much you collect of what you are owed, and how often claims are denied. A growing practice that does not watch them is flying without the instruments its own industry considers standard.

The Blind Spots That Cap Growth

The finance gaps in a growing healthcare or telehealth company cluster in four places. Any one of them can hold margins down while the top line rises.

  1. Days in AR and denied claims. Days in accounts receivable measures how long it takes to collect after care is delivered; a high number means earned revenue is sitting uncollected. Denials compound it. A meaningful share of claims are rejected on first submission across the industry, and every denied claim that is not reworked is revenue you earned and never banked. Watching these weekly, and working denials systematically, is often the fastest recovery of cash in the business.
  2. Cash-basis books. Many practices keep books on a cash basis, which records money when it moves and leaves profitability a guess. Care delivered this month but paid in sixty days, and costs incurred now but billed later, both land in the wrong period. Without accrual, you cannot see whether a service line is actually profitable, which is precisely the question a growing company needs answered. Deciding cash versus accrual is foundational here.
  3. Unmodeled payer and service-line mix. Different payers reimburse different amounts for the same service, and different service lines carry different margins. A company that has not modeled its mix cannot tell whether growth is improving or diluting its economics. In the telehealth example, modeling product penetration against an industry-standard rate showed exactly where additional cash could come from, turning a vague sense of underperformance into a specific plan.
  4. Manual data flow and compliance. When numbers are hand-keyed from a CRM or EHR into the accounting system, they are always late and always at risk of error, which is the same poor data quality that Gartner estimates costs organizations $12.9 million a year on average. For telehealth, protected health information (PHI) adds a compliance layer on top: any automation or outside analysis has to handle patient data correctly. Both are solvable, but they require someone who treats the data flow as finance infrastructure.

Speak to a CFO

If your healthcare company is growing while margins sit flat, the money is usually stuck in the revenue cycle and hidden by books that cannot show service-line profitability. A fractional CFO who understands healthcare economics can find it. Book a CFO strategy call with Ascent CFO Solutions and we will show you where earned revenue is leaking.

Talk to a CFO
An Experienced CFO is Within Reach

Get right-sized financial leadership from experienced CFOs ready to lead your team.

What the Telehealth Example Actually Needed

Return to the company breaking even when it should not have been. The work that closed the gap was not dramatic, and it is a fair template for what these engagements involve. First, the daily hand-keying from CRM to the accounting system was streamlined so the books were current and reliable, with patient data handled appropriately along the way. Then the financials were put on an accrual basis, so profitability by service line became visible instead of assumed. Then the payer and service mix was modeled, and product penetration was measured against the industry-standard rate to quantify the cash upside of closing that gap. What had looked like a company that simply could not make money turned out to be a company earning reasonable margins that were hidden by data lag and unmodeled mix.

The lesson is not that telehealth is uniquely hard. It is that healthcare economics reward a finance function built for them and punish one that is not. The same pattern shows up in clinics, specialty practices, and multi-location groups. Ascent CFO Solutions works with these businesses through our healthcare practice, and the fixes rhyme: collect faster, book on accrual, model the mix, and make the data trustworthy.

What Good Looks Like

A growing healthcare company with its finances in order watches a short list of revenue-cycle metrics every week — days in AR, denial rate, net collections — and works denials as a routine rather than a scramble. Its books are on accrual, so leadership can see which service lines and payers actually make money. Its payer and service mix is modeled, so growth decisions are made on economics rather than instinct. And its data flows from clinical and billing systems into finance without depending on someone retyping it each day. That combination turns a business that grows without getting richer into one where rising volume actually reaches the bank.

Frequently Asked Questions

Why is my healthcare practice growing but not more profitable?

Usually because earned revenue is stuck in the revenue cycle or the true economics are hidden by cash-basis books. Slow collections and denied claims mean you are not banking everything you earn, and without accrual accounting you cannot see which services or payers are actually profitable. Growth then adds volume without adding margin. Both problems are fixable once someone owns the revenue cycle and the books.

What revenue-cycle metrics should a growing healthcare company track?

At minimum, days in accounts receivable (how long collection takes), denial rate (how often claims are rejected), and net collection rate (how much of what you are owed you actually collect). The HFMA MAP Keys framework is the industry standard set of these measures. Watching them weekly, not annually, is what surfaces leaks while they are still fixable.

Should a medical practice use cash or accrual accounting?

For understanding profitability, accrual. Care is often delivered in one period and paid in another, and costs are incurred before they are billed; cash-basis accounting puts them in the wrong months and makes service-line profitability impossible to read. Accrual matches revenue and expense to when they are earned and incurred, which is what a growing practice needs to make good decisions.

How does telehealth change the finance picture?

Telehealth adds two wrinkles. Data often flows from a CRM or EHR that was not built to feed accounting, so numbers get hand-keyed and fall behind, and protected health information (PHI) means any automation or analysis has to handle patient data compliantly. The underlying economics are still revenue-cycle economics, but the data and compliance layer requires a finance function that treats both as infrastructure.

Do we need a full-time CFO to fix revenue-cycle problems?

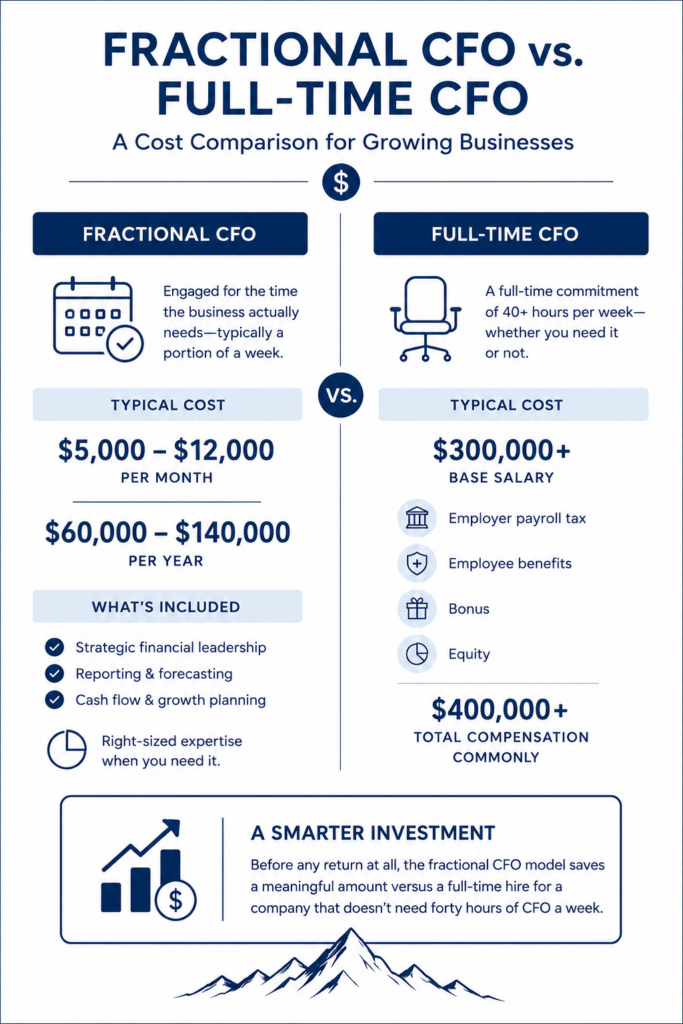
Not usually. What you need is finance leadership that understands healthcare economics and will own the revenue cycle, the accrual conversion, and the modeling. That can come from a fractional or interim CFO rather than a permanent hire, which is how many growing practices get senior financial leadership without full-time cost.

Turning Growth Into Margin

We help founders and leaders of healthcare and telehealth companies in Boulder, Denver, and across the country find the money stuck in their revenue cycle and build finance functions their economics reward. That work spans fractional CFO leadership, clean fractional accounting on an accrual basis, and the modeling that ties payer and service mix to cash. See how we work with the sector on our healthcare page, and for more on this: using fractional CFOs to help your healthcare practice thrive and interim CFOs in healthcare.

Book a CFO strategy call with Ascent CFO Solutions.

Deferred Revenue for SaaS: What It Is and What Founders Get Wrong Before a Raise

Key Takeaways

  • Deferred revenue is money you have collected but not yet earned. When a customer prepays for an annual subscription, the cash is yours, but the revenue is not; you recognize it over the term as you deliver the service. Until then it sits on your balance sheet as a liability.
  • SaaS subscription revenue is recognized ratably over the contract term, not all at once when the customer pays (the accounting standard behind this is ASC 606). A $120,000 annual prepaid deal becomes $10,000 of recognized revenue a month, not $120,000 in the month it was signed.
  • The most common and costly mistake is conflating bookings, billings, and revenue. Investors recalculate all three in diligence, and a deferred revenue schedule that does not tie out turns a number you were proud of into a credibility problem right when you are trying to raise.

A SaaS founder closes the biggest deal of the year: a $120,000 annual contract, paid in full up front. The cash lands, and it is tempting to treat that month as a $120,000 revenue month. Then the Series B diligence team asks a simple question. Why did revenue spike in March, why does it not match the subscription you actually deliver, and why does your deferred revenue balance not reconcile to your billings? Suddenly the best deal of the year is the reason the raise slows down.

This is the deferred revenue trap, and it catches more SaaS founders than it should. The concept is not complicated, but getting it wrong is expensive, because deferred revenue sits at the exact intersection of your books, your metrics, and the story you tell investors. Here is what deferred revenue actually is, how ASC 606 governs it, the three numbers founders keep confusing, and why all of it matters before you raise.

What deferred revenue actually is

Deferred revenue is payment you have received for a service you have not yet delivered. Andreessen Horowitz, in its widely used guide to startup metrics, puts it plainly: a SaaS company only gets to recognize revenue over the term of the deal as the service is delivered, so a large up-front booking goes onto the balance sheet in a liability line called deferred revenue.

The word “liability” surprises founders, because the cash feels like a win. It is a liability in the accounting sense: you owe the customer a year of service, and until you deliver it, you have an obligation, not earnings. Take that $120,000 annual deal. You collected $120,000 in cash, but in month one you have earned only one month of it. So $10,000 becomes revenue and $110,000 sits in deferred revenue. Each month after, another $10,000 moves from the deferred revenue liability to recognized revenue, until the balance reaches zero at the end of the term. That monthly movement is the deferred revenue waterfall, and a clean one is a sign of a finance function that knows what it is doing.

How SaaS revenue recognition actually works

The rules that govern this are set by ASC 606, the revenue recognition standard the Financial Accounting Standards Board (FASB) introduced in 2014 and the framework every serious buyer and investor expects you to follow.

ASC 606 works through a five-step model: identify the contract with the customer, identify the distinct performance obligations in it, determine the transaction price, allocate that price across the obligations, and recognize revenue as each obligation is satisfied. For a standard SaaS subscription, the practical result is straightforward: because the customer receives the benefit of the software continuously across the term, you recognize the revenue ratably, spread evenly over the contract, rather than all at once when they pay or sign.

Where ASC 606 gets genuinely tricky for SaaS is in the details that do not fit the simple subscription: implementation and onboarding fees, usage-based or overage pricing, multi-year deals with price escalators, and bundles that mix a software subscription with services. Each of these forces judgment about what the distinct performance obligations are and how to allocate the price. Getting those judgments right, and documenting them, is much of what a finance leader earns their keep on before a raise or a sale.

The three numbers founders keep confusing

Deferred revenue is really a symptom of a deeper issue: bookings, billings, and revenue are three different numbers, and treating them as one is one of the most common and costly mistakes a SaaS company makes.

  • Bookings are the total value of a contract a customer has committed to, including the parts you have not delivered or invoiced yet. Sign that $120,000 annual deal and you have booked $120,000.
  • Billings are what you have actually invoiced. If you billed the full year up front, billings are $120,000; if you bill quarterly, billings are $30,000 this quarter.
  • Revenue is what you have earned and recognized under ASC 606: the $10,000 a month you deliver.

Deferred revenue is the bridge between them. In fact, billings equals revenue plus the change in deferred revenue over the period. If your revenue in a quarter is $100,000 and your deferred revenue grew by $50,000, you billed $150,000. When a founder reports a booking or a billing as revenue, the metrics that investors live by, ARR (annual recurring revenue), growth rate, and net revenue retention, all come out wrong, and the error compounds across the model.

Why it matters before a Series A or B

Investors do not take your revenue number on faith. In diligence they rebuild it, recalculating ARR from your contracts, testing your deferred revenue schedule against your billings, and checking that your recognition policy holds up under ASC 606. A clean, defensible deferred revenue waterfall signals a company that runs on real financial discipline. A messy one signals risk, and risk gets priced into the valuation or stalls the round entirely.

This is why revenue recognition belongs in your fundraising preparation, not your post-close cleanup. The same discipline shows up in an investor-ready financial model and a fundraising data room that reconciles, and it is one of the first things an experienced SaaS finance leader tightens before a company goes to market.

What a deferred revenue cleanup looks like

A common version of this problem plays out like this. A growing SaaS company’s deferred revenue schedule drifts out of line with its actual contracts. Recognition does not quite match the terms, the schedule becomes something no one fully trusts, and the ARR and growth metrics get built on top of it anyway. By the time a raise is on the horizon, those numbers would not hold up to an investor’s recalculation.

The fix is unglamorous and effective: rebuild the deferred revenue schedule from the contracts and to ASC 606, then rebuild the metrics on the corrected base. It is ordinary work for a finance function that has done it before, and it is far cheaper to do in the months before a raise than in the middle of one.

Talk to a CFO

If you are heading toward a Series A or B and are not fully confident your revenue recognition would hold up under an investor’s diligence, that is worth resolving now rather than in the middle of the round. Ascent CFO Solutions builds and defends SaaS finance functions, from ASC 606 revenue recognition to the investor-grade metrics on top of it. Book a CFO strategy call with Ascent CFO Solutions.

Talk to a CFO
An Experienced CFO is Within Reach

Get right-sized financial leadership from experienced CFOs ready to lead your team.

Frequently asked questions

What is deferred revenue?

Deferred revenue is money a company has collected for goods or services it has not yet delivered. It is recorded as a liability on the balance sheet, because the company still owes the customer that future delivery. As the service is provided, the amount moves from deferred revenue to recognized revenue.

Is deferred revenue a liability or an asset?

A liability. It represents an obligation to deliver a service you have already been paid for. It becomes revenue, and leaves the liability line, only as you deliver over the term of the contract.

How does SaaS revenue recognition work for subscriptions?

ASC 606 requires you to recognize revenue as you satisfy your obligation to the customer. For a standard SaaS subscription, that means recognizing the revenue ratably across the contract term rather than when the customer pays or signs. Implementation fees, usage pricing, and bundled deals require additional judgment under the standard’s five-step model.

What is the difference between bookings, billings, and revenue?

Bookings are the total value a customer has committed to. Billings are what you have actually invoiced. Revenue is what you have earned and recognized under ASC 606. They are three separate numbers, and deferred revenue is the bridge between billings and revenue: billings equal revenue plus the change in deferred revenue.

When does deferred revenue become revenue?

As you deliver the service. For a subscription recognized ratably, a portion converts from deferred revenue to revenue each month across the term. A $120,000 annual prepaid deal converts at $10,000 a month for twelve months.

Why do investors care about deferred revenue?

Because it is where they check whether your revenue is real and your metrics are trustworthy. Investors recalculate ARR and growth from your contracts and test your deferred revenue schedule against your billings. A clean schedule builds confidence; a broken one raises questions about everything else in the model.

Get the number right before someone else checks it

Deferred revenue is the mechanism that decides whether your revenue, your ARR, and your growth rate are real, and it is one of the first things a sophisticated investor or buyer will test. The founders who raise cleanly are the ones whose revenue recognition was already right before anyone looked.

Ascent CFO Solutions helps SaaS and technology founders across the country build finance functions that hold up to investor scrutiny, from ASC 606 revenue recognition and a defensible deferred revenue schedule to the investor-grade metrics built on top of them. Through our fractional CFO and fractional accounting services, we make sure your numbers are ready before the diligence team arrives. Book a CFO strategy call with Ascent CFO Solutions.


Publishing handoff (not for publication):

  • SEO title: Deferred Revenue for SaaS: A Founder’s Guide Before You Raise
  • Meta description: What is deferred revenue, how does SaaS revenue recognition actually work, and why do bookings, billings, and revenue keep getting confused? A founder’s guide before you raise.
  • Suggested slug: deferred-revenue-for-saas
  • Primary keyword: “deferred revenue” (13,000 / KD 4, AI Overview) + “ASC 606” / “saas revenue recognition”; secondaries “arr vs revenue” (300 / KD 3), “bookings billings revenue.” ICP: SaaS founders (Investment-Ready Accelerators). Primary internal target: /sectors/saas-technology/ (SaaS cluster — links to the sector page and the SaaS resource per the SaaS growth plan).*

What Is a Quality of Earnings Report? A Founder’s Guide Before You Sell

Key Takeaways:
A quality of earnings (QoE) report is an independent analysis of how much of your company’s profit is real, recurring, and likely to continue under a new owner. It centers on adjusted EBITDA, revenue quality, and normalized working capital rather than on GAAP compliance.

A QoE and an audit answer different questions. An audit provides reasonable assurance that historical financial statements are free of material misstatement; a QoE asks whether the earnings behind those statements will repeat, which is what a buyer is paying for.

The math is unforgiving: at a 5x multiple, every $100,000 of EBITDA a buyer’s diligence team disallows takes roughly $500,000 off your purchase price. A sell-side QoE, commissioned months before you go to market, finds those problems while you can still fix them.

The letter of intent is signed. The price is agreed, the champagne is open, and then the buyer’s diligence team shows up and starts rebuilding your P&L line by line. Your EBITDA says $3 million. Theirs says $2.4 million. At the 5x multiple written into the LOI, that difference just cost you $3 million of purchase price, and you are still expected to close.

That rebuild is the quality of earnings analysis. A quality of earnings report is an independent, detailed examination of your company’s earnings, prepared by a transaction advisory team, that tells a buyer how sustainable and repeatable your profits really are. It typically takes four to eight weeks to complete, and it has become standard practice in nearly every private-market deal of consequence. Global M&A reached $4.8 trillion in 2025, the second-highest total on record according to Bain & Company, and the diligence machinery behind those deals has professionalized accordingly. The QoE sits at the center of it.

What Is a Quality of Earnings Report?

A QoE report is usually prepared by the transaction advisory practice of a CPA firm. It issues no opinion and provides no assurance; it is an analytical tool built for one audience, the party writing the check. A typical report contains:

  • An adjusted EBITDA schedule, walking from reported net income to a normalized EBITDA figure through a documented list of add-backs and adjustments.
  • A revenue analysis covering customer concentration, recurring versus one-off revenue, churn, pricing, and how revenue is recognized.
  • Margin analysis by product, service line, or customer, showing where the profit actually comes from and whether it is stable.
  • A proof of cash, which reconciles reported revenue and earnings to actual bank activity, month by month.
  • A net working capital analysis that establishes the normal level of working capital the business needs to operate.

Reports come in two flavors. A buy-side QoE is commissioned by the acquirer after a letter of intent, during exclusivity. A sell-side QoE is commissioned by you, before going to market, so you learn what a buyer will find while there is still time to fix it.

Who Orders a QoE, and When?

Buyers, almost always. Private equity firms treat a QoE as a non-negotiable condition of closing, strategic acquirers order one for any deal of size, and lenders financing the transaction frequently require it before committing debt. Since PE buyers typically hold companies for years before their own exit, they underwrite your earnings the way they will one day defend them to their own buyer.

There will be plenty of them to face. In Deloitte’s survey of 1,500 dealmakers, 79% of corporate leaders and 87% of private equity leaders expected deal volume to grow in the year ahead. An active market does not mean a forgiving one; diligence standards have tightened even as volume has recovered.

Sellers order QoE reports too, and the timing matters. A sell-side QoE commissioned 6–12 months before you go to market gives you a dry run of buyer diligence with time to act on the findings. Walking in without one means the buyer’s advisors define your EBITDA for you.

How Is a QoE Different From an Audit?

An audit is conducted under AICPA auditing standards and provides reasonable assurance that your historical financial statements, taken as a whole, are free of material misstatement. It answers a compliance question: do these statements fairly present what happened, under GAAP (Generally Accepted Accounting Principles)? A QoE answers an economic question: of the earnings those statements report, how much will keep showing up after the wire clears?

A company can pass its audit cleanly and still show poor earnings quality: one customer at 40% of revenue, a one-time windfall sitting in the run rate, owner expenses buried in cost of goods sold. The audit was never designed to catch any of that, because none of it is a misstatement.

AuditQuality of earnings
Core Question It AnswersAre the historical statements fairly presented under GAAP?Are the earnings sustainable and repeatable for a buyer?
Regulatory StandardAICPA auditing standards; opinion issuedNo prescribed standard; no opinion or assurance
Primary FocusBalance sheet accuracy, controls, complianceAdjusted EBITDA, revenue quality, working capital
OrientationBackward-lookingForward-looking, through historical evidence
Who relies on it?Shareholders, lenders, regulatorsBuyers, investors, deal lenders

The Four Areas a QoE Adjusts

Nearly everything in a QoE rolls up into four categories of adjustment.

1. Add-backs

Expenses that ran through the business but will not continue under a new owner: owner compensation above or below market rate, family members on payroll, personal vehicles and travel, the country club membership, one-off professional fees. Legitimate add-backs raise adjusted EBITDA and therefore your price, but every one must be documented to the invoice. Buyers discount the entire schedule when the first sloppy item appears.

2. One-time items

Revenue or costs that will not recur: a litigation settlement, an insurance recovery, pandemic-era government funds, a single unusually large project, the year a flood shut down the plant. These get stripped out in both directions, and sellers are consistently surprised at how many of their good years contain items a buyer refuses to count.

3. Revenue quality

Two companies with identical revenue can deserve very different multiples. The QoE examines how much revenue is recurring or contracted versus one-off, how concentrated it is among top customers, how much churns each year, and whether revenue is recognized in the right periods. Companies keeping cash-basis books face a particular reckoning here, because converting to accrual accounting re-times revenue and can reshape the growth story a seller thought they had.

4. Net working capital

Working capital (receivables plus inventory, minus payables, roughly) is the fuel a business runs on, and buyers expect a normal tank of it to convey with the company. The QoE establishes that normal level, which becomes the working capital peg in the purchase agreement; deliver less at close and the price adjusts against you, dollar for dollar. Founders systematically underestimate what is at stake here. PwC’s working capital study estimates €1.84 trillion of excess working capital is trapped on company balance sheets worldwide, and a seller who cannot explain their own working capital cycle will have the peg set for them.

What Buyers Look For, and Where Deals Get Re-traded

Retrading is the polite word for a buyer lowering the agreed price during diligence, and the QoE is where the ammunition comes from. The recurring targets:

  • The proof of cash. If reported revenue does not tie to bank deposits, the conversation changes from price to trust, and few deals recover from that.
  • Customer concentration. Any customer above 10–20% of revenue draws scrutiny, and buyers will call those customers before closing.
  • Margin durability. Declining gross margins beneath growing revenue is a pattern diligence teams are specifically trained to find.
  • Cash-to-accrual gaps. Timing differences that flattered recent results get unwound, and the restated trend is what gets priced.
  • Aggressive add-backs. Half-documented adjustments get struck from the schedule, and each strike multiplies: at 5x, a $200,000 add-back that fails review is $1 million off the price.

Harvard Business Review pegs the M&A failure rate at 70% to 90%, against more than $2 trillion companies spend on acquisitions every year. In the lower middle market, failure usually starts in diligence, at the moment the numbers stop matching the story. Sellers who have already found their own weak spots keep control of that moment.

Speak to a CFO

If a sale is even two years out, the financial statements a buyer will one day scrutinize are being written right now, month by month. Our CFOs get founders’ books, add-back schedules, and working capital analysis deal-ready long before a banker or buyer sees them. Book a CFO strategy call with Ascent CFO Solutions.

Talk to a CFO
An Experienced CFO is Within Reach

Get right-sized financial leadership from experienced CFOs ready to lead your team.

How to Prepare Before You Go to Market

The QoE rewards preparation more than any other step in a sale process, because every finding is cheaper to fix before a buyer is watching:

  • Move to accrual-basis, GAAP-compliant financials at least 12–24 months before a sale, so the restatement happens on your schedule instead of during exclusivity.
  • Run a disciplined monthly close, so revenue, cost, and margin land in the right periods and the trend line a buyer sees is real.
  • Build the add-back schedule now, with an invoice or agreement behind every line, instead of reconstructing it from memory under deadline.
  • Normalize owner compensation and separate personal expenses from the business well before diligence starts.
  • Study your working capital cycle by month, so you can argue for a fair peg instead of accepting the buyer’s.
  • Commission a sell-side QoE once you are within a year of going to market, and treat its findings as a punch list.

On cost: a sell-side QoE for a lower-middle-market company typically runs well into five figures. For comparison, a full year of fractional CFO support starts at $60,000 and covers the sustained preparation that determines what the QoE finds in the first place.

For the broader picture, start with our guide to preparing for the sale of your company and the financial questions to answer before you are acquired. If EBITDA still gets debated in your management meetings, our EBITDA explainer is the place to begin, our walkthrough of the M&A lifecycle shows where the QoE sits in the sequence, and our piece on a CFO’s role in exit planning covers the years before the process starts.

Frequently Asked Questions

How much does a quality of earnings report cost?

Most sell-side QoE engagements for lower-middle-market companies land in the low to mid five figures, with complex, multi-entity businesses running higher. Scope drives price: number of entities, quality of the underlying records, and whether a cash-to-accrual conversion is needed. Buy-side reports are paid for by the buyer.

How long does a quality of earnings analysis take?

Four to eight weeks is typical once the advisory team has your data. Messy records stretch the timeline, and in a live deal a stretched timeline is a cost in itself, since exclusivity periods are finite and buyer enthusiasm decays.

Do I need a QoE if my financials are audited?

Yes. Buyers commission a QoE on audited companies as a matter of course, because the audit addresses misstatement, and the QoE addresses sustainability. An audit strengthens your starting position and shortens the work, but it does not answer the buyer’s question.

What is an add-back in a QoE report?

An add-back is an expense added back to earnings because it will not continue under new ownership: above-market owner salary, personal expenses run through the business, or true one-time costs. Each documented, defensible add-back raises adjusted EBITDA, and at typical multiples each dollar of accepted add-back is worth several dollars of purchase price.

Should I get a sell-side QoE before going to market?

For most companies above a few million dollars in revenue, yes. It surfaces problems while you can still fix them, anchors negotiations on your numbers rather than the buyer’s, and signals to bidders that the process will be professionally run, which itself supports price.

What is a working capital peg?

The peg is the normalized level of net working capital the parties agree must be in the business at close, usually based on a trailing twelve-month average. Deliver more and the price adjusts up; deliver less and it adjusts down. The QoE’s working capital analysis is where that number gets established, which is why sellers should understand theirs first.

Know Your Number Before the Buyer Does

Sellers who walk into diligence with a defensible adjusted EBITDA keep their price; sellers who wait to be told their number rarely do. We help founders and CEOs in Boulder, Denver, and across the country prepare for exits, with clean accrual financials, documented add-backs, working capital analysis, and M&A support from CFOs who have sat on both sides of the table. Book a CFO strategy call with Ascent CFO Solutions.

financial red flags that drives away investors

Why Your Numbers Don’t Reconcile Across Systems (and How to Get One Source of Truth)

Key Takeaways

  • When your financials live in several disconnected systems, an accounting platform, a point-of-sale or operations tool, a purchasing system, and a pile of spreadsheets, the numbers stop agreeing. Budget-versus-actual becomes guesswork, and leadership ends up making decisions on stale or partial data.
  • The fix is a single source of truth: one consolidated layer where data from every system flows together on consistent definitions, so every report ties out and a dashboard shows the real position in near real time. For multi-entity or multi-currency companies, that consolidation is the whole game.
  • This is finance work, not just a software purchase, and the payoff shows up fast. One Ascent client, an international consulting firm running five separate QuickBooks entities across three currencies, went from scattered files to consolidated, board-ready dashboards.

You ask a simple question in a leadership meeting: are we over or under budget this quarter? Sales quotes a number from the CRM, operations quotes one from the project system, and finance quotes a third from the accounting software. None of the three agree, and the next twenty minutes go to arguing about whose number is right instead of what to do about it.

That is not a discipline problem or a careless team. It is a structural one. Your numbers live in systems that were never designed to agree, and until those systems share a single source of truth, you are steering the business on instruments that contradict each other. The good news is that this is a solvable finance problem, and solving it tends to pay for itself quickly. Here is why the numbers drift apart as you grow, what a single source of truth actually means, and what it looks like when a company gets it right.

Why the numbers stop agreeing as you grow

Early on, one accounting system and a spreadsheet cover the whole business. Everything of consequence runs through QuickBooks, and the founder can hold the real picture in their head.

Growth breaks that. You add a point-of-sale or operations platform, a purchasing system, a payroll provider, maybe a second entity or a second currency. Each system holds a genuine slice of the truth, and none of them holds the whole. Budgets get entered per-unit in one place and in bulk in another, so a straightforward budget-versus-actual comparison (measuring what you planned to spend or earn against what actually happened) becomes nearly impossible to produce cleanly. The month-end close drags because someone has to stitch the systems together by hand. And the reports that reach the board are a snapshot of where things stood weeks ago.

McKinsey’s work on the digital finance function describes the same pattern: teams end up spending more time reconciling data than analyzing it, while CEOs and boards increasingly expect finance to deliver real-time, data-enabled decision support. The gap between what leadership needs and what disconnected systems can produce is where growing companies lose visibility.

What “a single source of truth” actually means

A single source of truth does not mean forcing your entire business onto one platform. It means building one consolidated layer where the data from all of your systems flows together, gets reconciled, and reports off consistent definitions. The accounting system stays. The operations platform stays. What changes is that their numbers meet in one place and are made to agree.

McKinsey’s guidance to CFOs is to advocate for exactly this: a common data layer flexible enough to accommodate a changing business while preserving one reconciled version of the numbers, with the reconciliation automated so the information can be current rather than weeks old. The CFO is well positioned to lead this, because finance is both the biggest consumer and the biggest provider of consistent information across the company.

The part that is easy to underestimate is definitions. Getting the plumbing right matters, but so does agreeing on what a “unit” is, what counts as revenue versus deferred revenue, and which costs belong to which segment. Two systems can be wired together perfectly and still disagree because they define the same word differently. A real single source of truth settles the definitions first, then the data.

Multi-entity and multi-currency: where it gets hardest, and matters most

The problem compounds when a company runs multiple legal entities or operates in more than one currency. Now you are not just reconciling systems, you are consolidating entities: eliminating intercompany transactions (sales or loans between your own entities that would otherwise double-count), translating currencies, and rolling everything up into one set of financials that a lender, an investor, or a board can trust.

This is multi-entity accounting, and it is precisely where a consolidation layer earns its keep. Done by hand in spreadsheets, it is slow, error-prone, and dependent on whoever built the workbook. Done through a proper consolidated reporting layer, it becomes a report you can run on demand.

A real example: five QuickBooks files to one dashboard

An international consulting firm we work with had reached this exact wall. The company ran five separate QuickBooks entities across three currencies, with no single place that showed the whole business. Leadership could see each piece, but not the consolidated picture, and pulling one together was a manual project every time someone asked.

We built that consolidated view for them and turned it into dynamic financial dashboards for the executive team, the CEO, and the board, while streamlining their expense-management process and keeping the whole thing transparent and access-controlled. The result was that leadership could finally see the entire company, across all five entities and three currencies, in one place and close to real time, instead of waiting on a hand-built roll-up. That is the difference a single source of truth makes: the same underlying business, suddenly legible.

From dashboard to decisions

Consolidation is not the goal in itself. A clean single source of truth is what makes the decisions above it possible. With one reconciled set of numbers, budget-versus-actual becomes a report you trust rather than a debate. Cash position is visible without a fire drill. Margin by product, segment, or entity becomes something you can actually see, which is often where a growing company discovers that one line of business is carrying the others. And the forecast rests on numbers that reconcile, so the plan you commit to is built on the real position rather than a stale approximation.

Visibility, in other words, is not a reporting nicety. It is the foundation the rest of your financial decisions stand on, and it is a core part of building a finance function that scales.

Speak to a CFO

If your leadership meetings keep stalling on whose number is right, that is a sign your systems need a single source of truth, and it is a solvable problem. A fractional CFO and a data and analytics team can consolidate your systems, settle the definitions, and stand up dashboards your leadership and board can rely on. Book a CFO strategy call with Ascent CFO Solutions.

Frequently asked questions

What does “single source of truth” mean in finance?

It means one consolidated, reconciled set of numbers that every report draws from, rather than several systems each holding a partial and slightly different version. It does not require putting the whole business on one platform. It requires a layer where the data from your systems is brought together on consistent definitions so the reports agree.

How do I get financial visibility across multiple systems?

Consolidate the data into one place, settle the definitions of your key metrics, automate the reconciliation so the numbers stay current, and put a dashboard on top that shows the real position. The systems themselves can stay where they are; what changes is that their data meets and agrees in one consolidated layer.

What is multi-entity accounting, and why is consolidation hard?

Multi-entity accounting is producing financials for a company that operates through more than one legal entity, often across currencies. Consolidation is hard because you have to eliminate intercompany transactions, translate currencies, and align each entity’s books to the same definitions before the numbers can roll up into one trustworthy set of statements.

Do I need new software, or can I fix this with what I have?

Often you can get a long way with the systems you already run, connected through a consolidation and reporting layer. The right answer depends on your setup, but the fix is usually less about buying another platform and more about building the layer that makes your existing systems agree.

How do disconnected systems affect budget vs. actual?

Badly. If budgets are recorded one way in one system and actuals accumulate another way in another, comparing them cleanly is nearly impossible, and the comparison you do produce arrives late. A single source of truth is what makes budget-versus-actual a reliable, on-demand report.

Is a financial dashboard worth it for a smaller company?

Yes, once the business runs on more than one or two systems or more than one entity. The value is not the visual; it is the consolidated, reconciled data underneath it, which turns finance from a rear-view report into something leadership can steer with.

See the Whole Business, Not the Pieces

The companies that make good decisions as they scale are the ones whose leadership can see the entire business in one place, in numbers everyone trusts. The ones stuck arguing about whose figure is right are usually not short on data. They are short on a single source of truth.

We help founders and CEOs of growth-stage companies in Boulder, Denver, and across the country consolidate their systems, settle their definitions, and build the dashboards and reporting their leadership and board can rely on. Through our fractional CFO and data analytics services, we turn a tangle of disconnected systems into one clear view of the business. Book a CFO strategy call with Ascent CFO Solutions.


  • SEO title: Financial Visibility: Why Your Numbers Don’t Reconcile
  • Meta description: When your financials live in disconnected systems, the numbers stop agreeing. Why it happens, and how a single source of truth restores budget-vs-actual and clarity.

What’s the ROI of Hiring a Fractional CFO for a $5M–$20M Business?

As your team considers bringing on a fractional CFO, the natural question arises: what’s the real ROI on this temporary hire? How does it compare in value to a full-time CFO? The honest answer is that the return is real and usually several times the cost, but you have to know where to look for it. Here is where the value actually comes from, with the kind of numbers that make it concrete, because vague claims about value are worth nothing to a founder weighing a real decision.

Start With What It Actually Costs

Set the baseline first. A full-time CFO at a growing company runs $300,000 and up in total compensation, frequently with equity and bonus on top, plus the cost and risk of recruiting for a senior role you may not be able to keep busy full-time at $8M in revenue.

A fractional CFO is engaged for the time the business actually needs, which for a $5M–$20M company is typically a portion of a week. The cost commonly lands somewhere in the range of $5,000 to $12,000 a month depending on scope and intensity, call it $60,000 to $140,000 a year. Compare this against a full-time equivalent of $300,000-plus salary – before employer payroll tax, employee benefits, bonus, and equity. So before any return at all, the model saves a meaningful amount versus a full-time hire for a company that does not need forty hours of CFO a week.

That is the cost side. Now the return, in the categories where it actually shows up.

Where the Return Comes From

1. Cash freed from working capital

This is the most concrete and often the fastest payback. A fractional CFO who tightens the cash conversion cycle, collecting in 40 days instead of 60, right-sizing inventory, renegotiating vendor terms, frees cash that was trapped inside the operation. For a $10M business carrying a 60-day cycle, shaving 15 days off can free several hundred thousand dollars of cash, money you would otherwise have borrowed or raised. That is not a soft benefit. It is cash back in the account, and it frequently covers the annual cost of the engagement several times over in the first year alone.

2. Capital raised, and raised on better terms

When a company takes on debt or raises equity, the quality of its financials and forecasts directly affects the outcome. A fractional CFO who walks into a lender conversation with investor-grade financials and a defensible model gets a larger facility at a lower rate than a founder presenting cash-basis books and a forecast in their head. On a $2M credit facility, a single point of rate difference is $20,000 a year. On an equity raise, the difference between a clean process and a messy one can be a materially better valuation or the difference between closing and not closing. The CFO’s fee is small against the size of the capital decisions they shape.

3. Margin and profitability improvement

A fractional CFO who breaks blended numbers down by customer, product, and line shows you which parts of the business actually make money. Acting on that, pricing up the underpriced work, cutting or fixing the lines that lose money, focusing growth on the profitable segments, moves the margin. On a $10M business, a two-point gross margin improvement is $200,000 a year, recurring. Margin gains compound, and they survive long after the engagement, which makes this one of the highest-return categories over time.

4. The expensive decisions you don’t make

This one is invisible by nature, which is exactly why it is undervalued. The location that looked profitable but would have drained cash for two years. The hire made too early against a sales ramp that was never going to close in time. The contract signed without anyone modeling what it did to working capital. A fractional CFO who models the big decisions before you commit prevents the costly wrong ones. A single avoided mistake at this scale, a bad expansion, a six-figure cash surprise, can exceed a full year of the CFO’s cost. You never see this return on a statement because the loss never happened, but it is among the largest.

5. Faster, better decisions

Beyond avoiding the wrong moves, a fractional CFO lets you make the right ones with confidence and speed. The founder who can see, in a model, what a decision does to cash and the business over the next eighteen months commits faster and more often than the one waiting until they feel sure. In a growing market, the cost of a decision delayed three months because nobody could analyze it is real, even if it never gets measured. Decision speed backed by analysis is a return that does not fit neatly on a spreadsheet but shows up in how fast the company can move.

6. A higher number when you sell

For a founder thinking about an eventual exit, this is the largest category of all. A company sells on a multiple of EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization), and a fractional CFO who improves margins, cleans the financials, builds a defensible adjusted-EBITDA story, and reduces the business’s dependence on the founder raises both the multiple and the base number. On a business selling for eight times EBITDA, every $100,000 of durable EBITDA the CFO helps build is worth $800,000 in enterprise value. Years of fractional CFO fees can be returned many times over in a single transaction.

7. Your time and focus back

The founder who is doing the financial thinking themselves, at night, between everything else, is paying a cost that does not appear anywhere. A fractional CFO takes the financial weight off the founder’s plate and gives the largest decisions a real owner, freeing the founder to run the business they are actually best at running. Hard to put a number on, easy to feel, and consistently one of the first things founders mention after the fact.

Doing the Math for Your Own Business

Add it up and the pattern is consistent. A $5M–$20M company paying $60,000 to $140,000 a year for fractional CFO leadership is typically looking at returns, in freed cash, better capital terms, margin gains, and avoided mistakes, that run several times the cost in the first year, before counting the exit-value lift that may dwarf everything else later. The reason the ROI feels unproven before you start is that the costs are visible and the returns are diffuse. Once you know the categories, the math usually answers itself.

The honest caveat: the return depends on the CFO actually doing this work and on the business having room to improve. A company with already-pristine cash management, perfect margins, and no upcoming capital decisions has less to gain. Most $5M–$20M companies are not that company. Most have working capital sitting idle, blended numbers hiding unprofitable segments, a capital decision on the horizon, and big choices being made without anyone modeling them. That is where the return lives.

Speak to a CFO

The fastest way to answer the ROI question for your specific business is to have someone look at it and tell you where the return would actually come from, the freed cash, the margin, the capital terms, the decisions ahead. That conversation is concrete, not theoretical, and it usually surfaces the answer quickly.

Talk to a CFO
An Experienced CFO is Within Reach

Get right-sized financial leadership from experienced CFOs ready to lead your team.

Book a CFO strategy call with Ascent CFO Solutions and get a straight read on what fractional CFO leadership would actually return for your business.

FAQs About Fractional CFO ROI

1. How fast does a fractional CFO pay for itself?

For most $5M–$20M companies with room to improve, the first measurable return, usually cash freed from working capital, arrives within the first few months and often covers the annual cost on its own. The larger returns, margin improvement, better capital terms, avoided mistakes, accrue over the engagement. Exit-value lift, if a sale is on the horizon, lands later and is typically the largest of all.

2. What does a fractional CFO actually cost?

Commonly $5,000 to $12,000 a month for a $5M–$20M company, depending on scope and how intensive the engagement is, which works out to roughly $60,000 to $140,000 a year. Compare that to $250,000-plus in total compensation for a full-time CFO, for a company that usually does not need a CFO forty hours a week.

3. Isn’t this only worth it if we are about to raise or sell?

A raise or a sale makes the return especially large, but it is not the only source. Freed working capital, margin improvement, better lending terms, and avoided mistakes accrue to companies that have no transaction on the horizon at all. The everyday return, cleaner cash, sharper decisions, better margins, stands on its own. A transaction just adds a large bonus category on top.

4. How do I measure the ROI if some of it is invisible?

Track what you can: cash freed from the working-capital cycle, rate and size improvements on financing, margin movement by segment. Acknowledge the categories you cannot fully measure, avoided mistakes and decision speed, while recognizing they are real. The visible categories alone usually justify the cost; the invisible ones are upside. The key is not to dismiss a return simply because it does not arrive with a label.

5. What if we already have a controller and a bookkeeper?

Then you have the backward-looking function covered, accuracy, the close, compliance, and you are missing the forward-looking layer, which is where the ROI in this article comes from. A fractional CFO sits above the accounting function you already have. It is not a replacement for your controller; it is the strategic layer your controller’s role does not include.

The Return Is Real, You Just Have to Know Where It Lives

The founders who hesitate on a fractional CFO are usually doing honest math with incomplete categories. They see the monthly cost and weigh it against a vague sense of “strategic value,” and the case looks shaky. The founders who say yes have learned to see the return where it actually shows up: in cash freed, margins moved, capital terms improved, mistakes not made, and an eventual exit worth more. By those categories, for most companies between $5M and $20M, the math is not close.

We help founders and CEOs of growth-stage companies across the country capture exactly these returns, freeing trapped cash, improving margins, securing better capital, and making the big decisions with someone modeling them first. Through our fractional CFO services, we deliver CFO-level leadership scaled to what your business actually needs, at a fraction of the full-time cost.

Book a CFO strategy call with Ascent CFO Solutions and find out what the real return would be for your business.

An Experienced CFO is Within Reach

Start Building Financial Clarity Today